Most budgets fail within three months. Here's how to build one that fits your real life, your real income, and your real goals.
- October 15, 2026
AceShowbiz - Most budgets die quietly in a notes app around week three. Not because people are lazy or bad with money, but because the budget they built was designed for a fictional version of themselves — someone who never grabs takeout on a stressful Tuesday or forgets that car registration is due in April.
A budget that works isn't the most detailed one. It's the one you'll still be using in six months. According to a 2026 Debt.com survey, about 80% of Americans say they keep a budget, but roughly two-thirds of them admit they don't stick to it consistently. That gap between "having a budget" and "using a budget" is where the real work happens.
Here's how to close that gap — not by becoming a spreadsheet wizard, but by building a system that bends instead of breaking.
Start With What You Actually Spend, Not What You Think You Should
The biggest mistake people make is building a budget around aspirational numbers. You decide you'll spend $300 on groceries, $80 on eating out, and $50 on "fun." Then reality hits: you spend $520 on groceries, $240 on eating out, and you have no idea where the rest went.
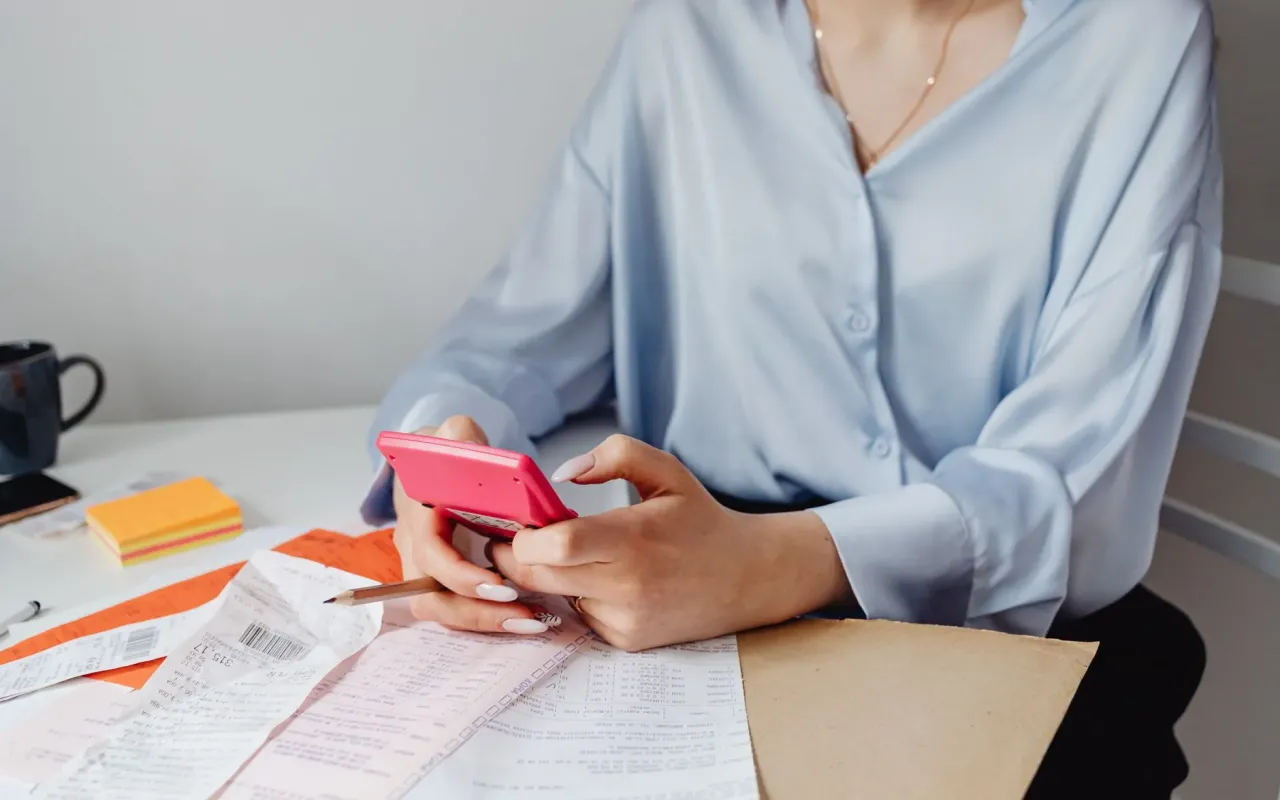
Before you set a single limit, pull your last two to three months of bank and credit card statements. Categorize every transaction. Yes, it's tedious. Yes, it's worth it. You're looking for your real baseline, not your fantasy baseline.
Most people discover two things. First, their spending is higher than they guessed in at least three categories. Second, a surprising chunk of money goes to subscriptions and small recurring charges they forgot existed. The average American spends around $219 a month on subscription services, according to a 2026 C+R Research study — and most people underestimate that number by roughly $100.
Practical tip: Use a free tool like Mint's replacement (Monarch, Copilot, or even a simple spreadsheet) to auto-categorize transactions. Spend 30 minutes tagging anything that looks unfamiliar. You'll likely find $50–$150 a month in spending you didn't consciously choose.
Pick a Budgeting Method That Matches Your Brain
There is no single "correct" budgeting method. There are only methods that fit how you naturally think about money. Trying to force yourself into the wrong one is like wearing shoes two sizes too small — you'll take them off the first chance you get.
The 50/30/20 Rule — Best for Beginners
This splits your after-tax income into three buckets: 50% for needs (rent, groceries, utilities, minimum debt payments), 30% for wants (dining out, hobbies, travel), and 20% for savings and extra debt payoff. It's simple, flexible, and works well if your income is steady.
The catch: if you live in an expensive city, 50% might not cover rent alone. In that case, adjust the ratios — maybe 60/20/20 — rather than abandoning the framework entirely.
Zero-Based Budgeting — Best for Detail-Oriented People
Every dollar gets assigned a job. Income minus all planned spending and saving equals zero. This method gives you total control and works beautifully if you enjoy tracking. It also tends to fail hard if you don't, because it requires monthly maintenance.
Pay Yourself First — Best for Impulsive Spenders
You automate savings and bill payments the day you get paid, then spend what's left without guilt. This works well for people who hate tracking every purchase. The trade-off is you need enough income cushion to make it safe.
Practical tip: Try one method for a full month before switching. Most people quit too early and assume the method is broken when really they just haven't adapted yet.
Build In a Buffer So You Don't Quit When Life Happens
Every budget fails the same way: an unexpected expense shows up, you blow past your limits, you feel like a failure, and you stop tracking. The fix isn't discipline — it's a buffer.
Set aside 5–10% of your monthly income as a "miscellaneous" or "life happens" category. This is money you fully expect to spend on things you can't predict: a prescription, a birthday gift, a parking ticket, a friend's last-minute wedding.
When you have a buffer, an unexpected $80 expense doesn't wreck your budget. It just comes out of the buffer. You stay on track, your confidence stays intact, and you keep going.
Pair this with a small emergency fund — even $500 to start — so that a bigger surprise doesn't force you onto a credit card. A 2026 Federal Reserve survey found that 37% of Americans couldn't cover a $400 emergency with cash. Having even a modest cushion changes how you feel about money day to day.
Practical tip: Label the buffer something honest like "Stuff I Forgot About." It sounds silly, but it removes the shame when you use it, and shame is what kills budgets.
Review and Adjust Monthly — Not Once a Year
A budget is not a document you set and forget. It's a living plan that needs a check-in at least once a month. Pick a day — the first Sunday, the day you get paid, whatever works — and spend 20 minutes reviewing.
Ask three questions: What went over? What went under? What changed in my life this month? Maybe your car insurance went up. Maybe you got a raise. Maybe you're planning a trip next quarter. All of those should shift the numbers.
People who review monthly are dramatically more likely to stick with budgeting long-term. It's not because they're more disciplined — it's because they catch problems while they're small. A $40 overspend in month one is easy to fix. A $400 overspend in month six feels like a crisis.
Adjustments are not failures. They're the entire point. A budget that never changes is a budget that isn't tracking reality.
Practical tip: Keep a running note on your phone called "Budget Adjustments." Whenever something feels off — a category that's always tight, a bill that's crept up — jot it down. Review it during your monthly check-in.
Make It Automatic and Make It Visible
Willpower is a terrible budgeting tool. It runs out. Systems don't. The two things that make a budget stick are automation and visibility.
Automate the boring stuff: bills on autopay, savings transfers on payday, retirement contributions straight from your paycheck. Every dollar that moves without you thinking about it is a dollar you can't accidentally spend on something else.
Then make the rest visible. Put a sticky note on your laptop with your dining-out limit. Set your banking app to send a notification when your checking account drops below a certain number. Use a budgeting app that shows your remaining balance in each category at a glance.
Visibility matters because spending happens in the moment, not in a spreadsheet. If you don't know your grocery budget is nearly gone when you walk into the store, you're budgeting blind. A 2022 study from the University of Wisconsin found that people who checked their account balances daily spent less overall — not because they were stricter, but because they were more aware.
Practical tip: Set up a weekly text or email from your bank showing your balance. Reading that one number once a week changes your spending more than any app feature will.
Give Your Budget a Goal Worth Caring About
The final piece is the one most budgeting advice skips: purpose. A budget with no goal is just restriction. And restriction, on its own, is exhausting. You need a reason that matters more than the $6 latte.
Maybe it's paying off $12,000 in credit card debt in 18 months. Maybe it's a $3,000 emergency fund so you stop feeling anxious every time your car makes a weird noise. Maybe it's a two-week trip to Japan next spring. Whatever it is, write it down and put it somewhere you'll see it.
When your budget connects to a specific, emotional goal, the trade-offs stop feeling like punishment. Skipping takeout on Friday isn't deprivation — it's $40 closer to something you actually want.
And here's the honest part: your budget will never be perfect. You'll have months where you blow it completely. The people who succeed aren't the ones who never mess up — they're the ones who open the spreadsheet again the next month anyway.
Practical tip: Name your savings account after your goal. "Japan Trip 2026" hits differently than "Savings Account 2." Every time you see it, you're reminded why you're doing this.
Start small. Pick one method, track for 30 days, and adjust. A budget that's 80% right and actually used beats a perfect one you abandon by February.